Florida continues to attract business growth and real estate investment, creating opportunities for commercial development. For developers and investors, identifying the right property is only part of the equation. How you finance the project can shape your budget, timeline, and long-term return.
Commercial real estate financing is not one-size-fits-all. A loan used to build a property has a different purpose and structure than a loan used to buy a completed building. Understanding those differences can help you make better decisions before construction begins and prepare for what comes after completion.
What Is a Construction Loan?
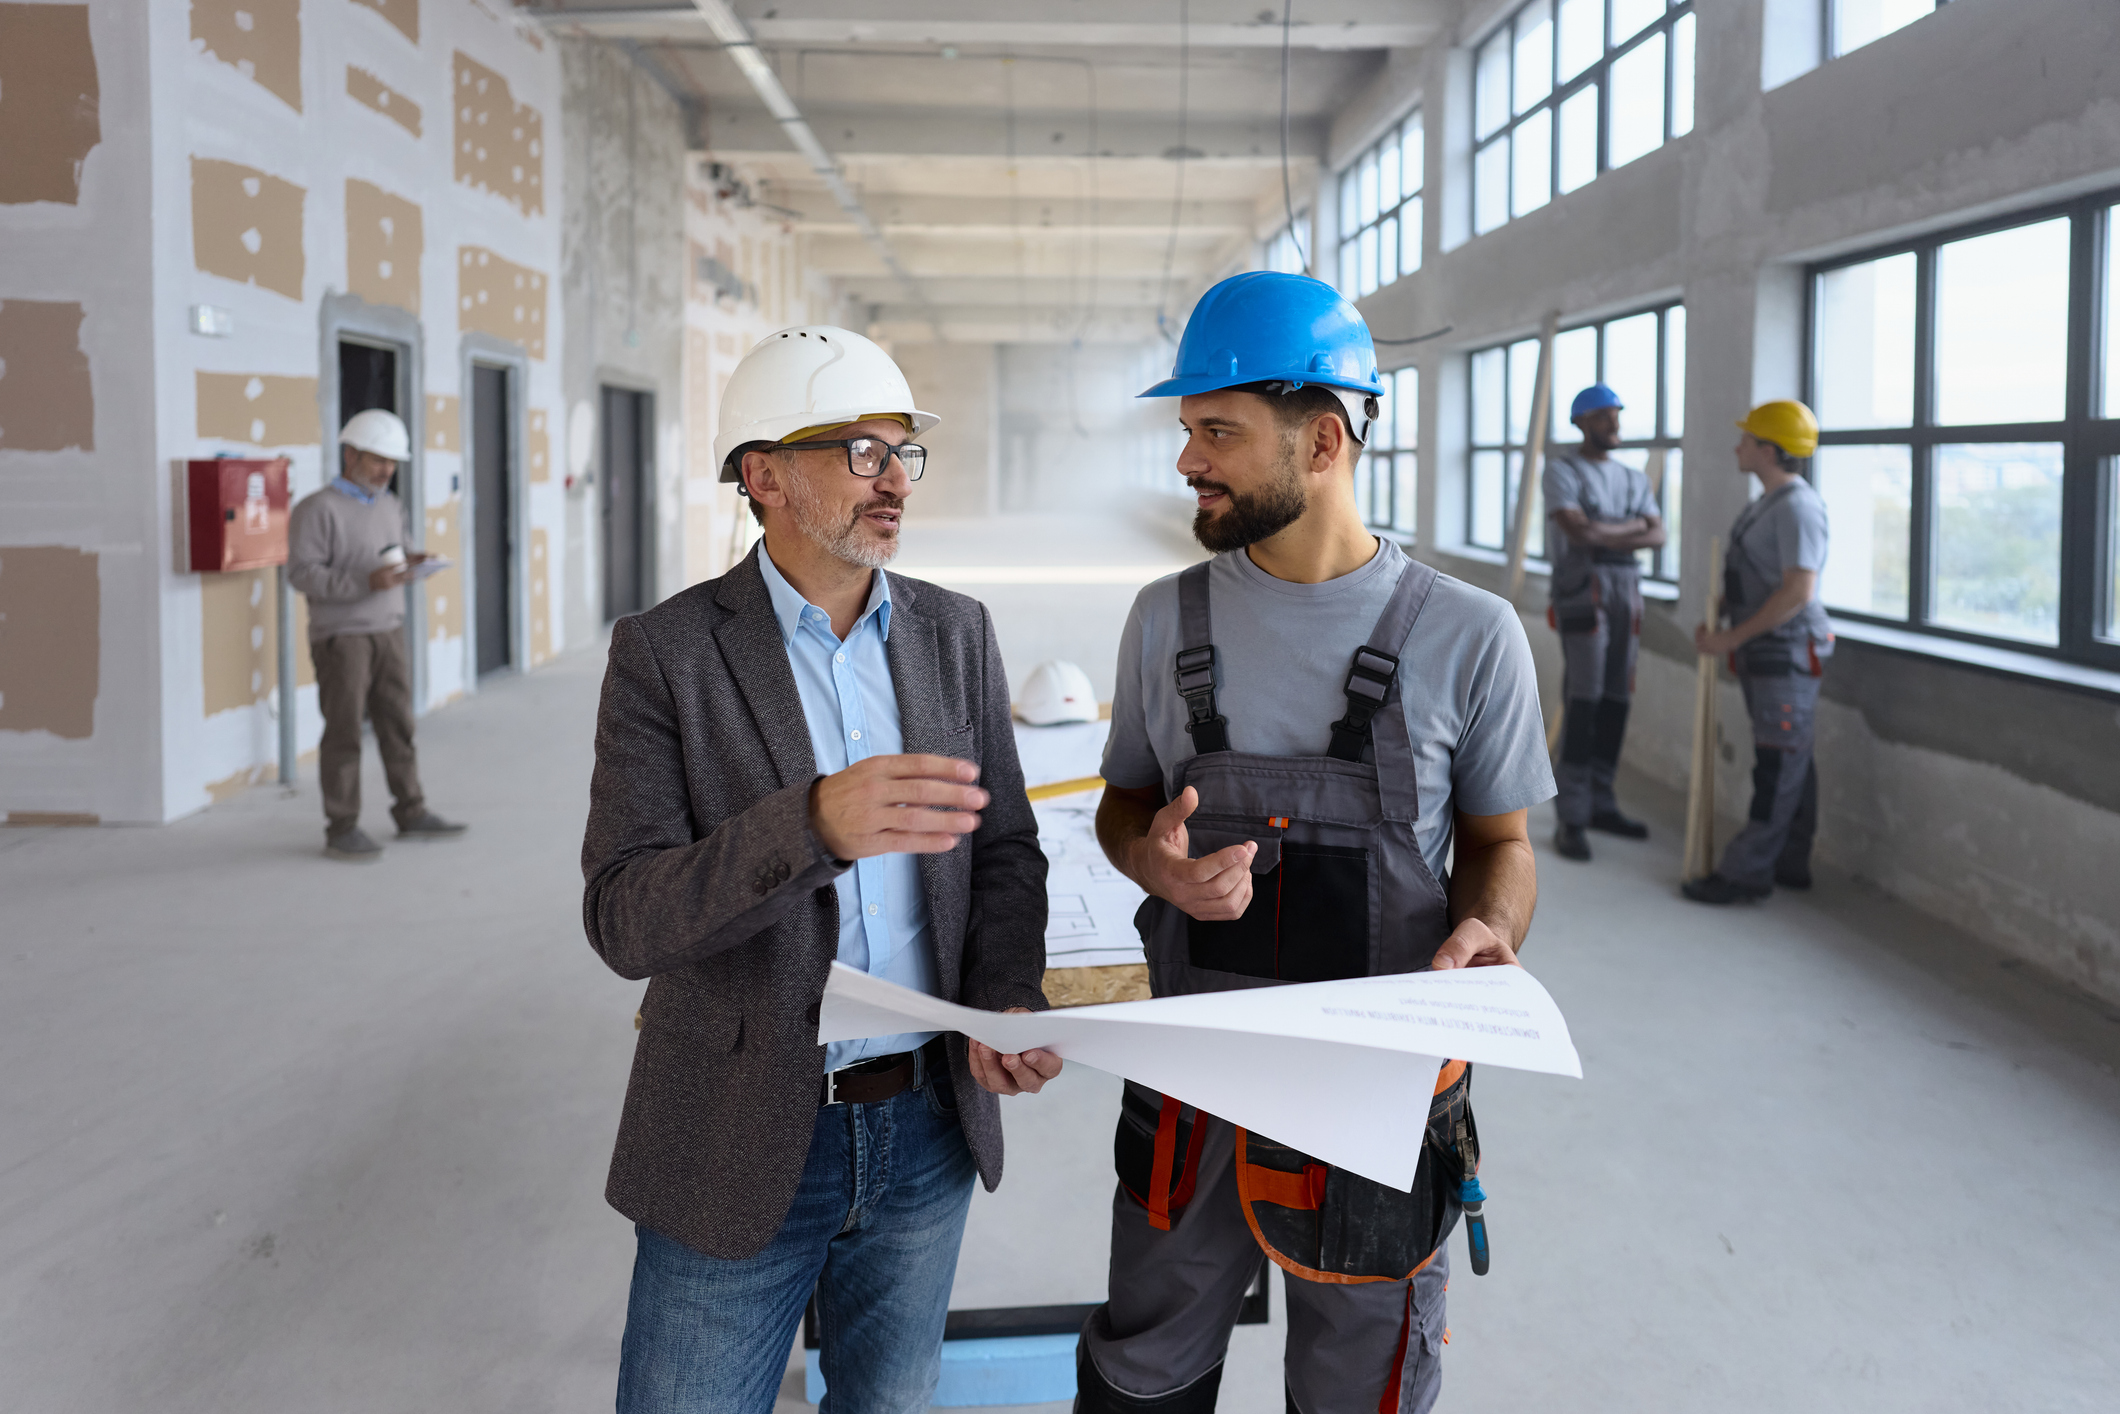
A construction loan is short-term financing designed to fund a property’s development, renovation, or expansion. Different types of construction loans help finance a project while work is underway. Lenders generally secure traditional commercial mortgages with a completed or income-producing property.
Instead of receiving the full loan amount at closing, borrowers typically access construction funds through a series of draws. Each draw corresponds to an approved project stage, and lenders may require inspections or documentation before releasing additional funds.
Construction financing may cover eligible costs such as land acquisition, site preparation, labor, materials, and permits.
Common Types of Construction Financing
The appropriate structure depends on the property and the work being completed.
● Ground-up construction loans help finance a new commercial property that is building on vacant or reusable land.
● Renovation or expansion loans can support major improvements to an existing property, including additions or substantial upgrades.
Bridge financing can also help when a project needs short-term capital before permanent financing is available. It may help cover a timing gap, an acquisition, a repositioning, or another temporary need, depending on the project and the lender.
Why Commercial Real Estate Financing Matters
Commercial real estate financing includes lending solutions for acquiring, building, improving, refinancing, or holding business and investment properties. The structure varies based on the property, its intended use, the borrower’s strength, and expected cash flow.
For developers, financing can make it possible to move forward without funding the entire project with equity. That can preserve liquidity for other business needs while creating a structure aligned with the development timeline.
Financing can also help you manage project risk with better focus. Lenders often review construction budgets, contractor information, projected completion dates, leases, and market conditions before approving a transaction. This due diligence can create a clearer framework for how the project will receive funding and monitoring.
Exploring New Construction Financing Options
Bank financing is one of the most common options for commercial construction, but it is not the only one. Depending on the project, borrower profile, and intended use of the property, you may consider other sources.
Traditional bank loans generally offer a structured underwriting process. This suits borrowers with strong financials, sufficient equity, and a clearly defined project. Private lenders may offer greater flexibility in certain situations, though pricing and terms can vary considerably.
SBA financing may also be available for qualifying owner-occupied commercial real estate projects. For eligible businesses, certain SBA loan programs can support the purchase, construction, expansion, or improvement of business property.
Some projects may consider other alternatives, including private investment or crowdfunding platforms. These options can carry different costs, control requirements, and risks, so evaluate them carefully.
How Lenders Evaluate Loan Amounts and Terms
Lenders base the amount they’re willing to provide on more than the construction budget. A lender will typically evaluate the overall feasibility and the borrower’s ability to complete and repay the loan.
Common considerations include:
● The borrower’s financial strength and experience
● The project budget and amount of borrower equity
● The value of the completed property
● Expected cash flow, occupancy, or lease activity
● The construction timeline and contractor experience
● Market conditions and the proposed exit strategy
Your goal is to pick a loan amount and repayment plan that support the project. It should not put extra pressure on cash flow. A larger loan is not automatically a better loan. The right structure should account for expected costs, contingencies, interest expense, and the post-construction financing plan.
Property Development Loans and LTV
Lenders design property development loans with the understanding that the property will change during the loan term. Because the asset may be in the process of completion, lenders use variables to assess it. This includes using budgets, plans, appraisals, and projected values to make decisions.
One important measure is the loan-to-value ratio, or LTV, which compares the loan amount to the property’s value. In construction lending, lenders may also review the loan-to-cost ratio, which compares the loan amount to the total cost of the project.
A lower LTV generally means the borrower is contributing more equity relative to the property’s value. That can affect approval, pricing, required reserves, and other loan terms. The acceptable ratio will depend on the lender, property type, borrower profile, and transaction risk.
Construction Loans vs. Commercial Mortgages
Construction loans and commercial mortgages serve different stages of a property’s life cycle.
A construction loan is generally temporary. This loan funds the work while you build or substantially improve the property. Repayment terms may include interest-only payments during construction. They expect the borrower to repay or refinance the loan when the project is complete.
Borrowers typically use a commercial mortgage loan once the property reaches completion. This way, evaluators can assess it as a stabilized asset.
The lender may focus more on how the property’s manager runs the property. It may look at occupancy and cash flow. It may also assess whether the property can support long-term debt.
For many projects, the financing strategy anticipates this transition early. Once construction is complete, the borrower may refinance the construction loan into permanent financing. Some transactions may also use a construction-to-permanent structure, reducing the need for a separate closing later.
Bringing Construction and Commercial Property Financing Together
The strongest financing strategy begins before construction starts. You should know the project budget and the equity you can add. You should also know how much time you have to finish the work and learn how property financing works after construction ends.
Think beyond the initial loan approval. Ask how the lender will handle draws and budget changes. Also ask which documents to provide and which conditions to meet before the lender makes permanent financing available.
For Florida developers and investors, this can be especially important when construction costs, insurance expenses, interest rates, and local conditions influence project economics.
Choosing the Right Financing for Your Commercial Project
A construction loan can be an effective tool when it matches the project’s needs and fits within a broader financing plan. Before moving forward, compare lenders, understand the cost of borrowing, and make sure the structure aligns with both the construction phase and the completion.
If you are planning a commercial property project in Florida, start the financing conversation early. Even if you’re looking for the right commercial loan option in Florida, Amerant Bank’s Commercial Banking team can help.
Related posts